Author: Cathy’s Real Estate Insights

  • Texas Apartment Surplus Isn’t Evenly Spread Across Markets

    Texas has added a large number of apartments in recent years, but the resulting supply pressure varies by market. Looking only at statewide totals can hide where the imbalance is most concentrated.

    A Spring 2026 analysis from the Texas Real Estate Research Center compared each market’s share of the apartment surplus with its share of total apartment inventory. Dallas–Fort Worth’s shares were close: about 35% of the net surplus compared with 36% of inventory. Houston accounted for about 22% of the surplus and 29% of inventory. Austin stood out in the other direction, representing about 22% of the surplus but 13% of inventory. San Antonio accounted for about 12% of the surplus and 9% of inventory.

    Those figures show why local conditions matter. A statewide headline about apartment oversupply does not tell an investor how a specific submarket, property type, or rent range is performing. Competition from new deliveries, population and household growth, and the pace of leasing can differ considerably from one city to another.

    For owners, investors, and renters, the practical takeaway is to look closely at the specific market and property. Ask how much new supply is nearby, how quickly comparable units are leasing, and whether rents and concessions are changing. Those details can offer a clearer view of risk than a statewide average.

    Apartment markets can rebalance over time as new construction slows and demand absorbs available units. Until then, a careful, local analysis is essential before making a purchase, development, or leasing decision.

    Source: Daniel Oney, “The Texas Apartment Surplus Built Up Since 2020 Is Not Evenly Spread Across Markets,” Tierra Grande: The Journal of Texas Real Estate Research, Spring 2026, p. 3.
  • Are You Diversified?

    Are You Diversified?

    Are You Diversified?

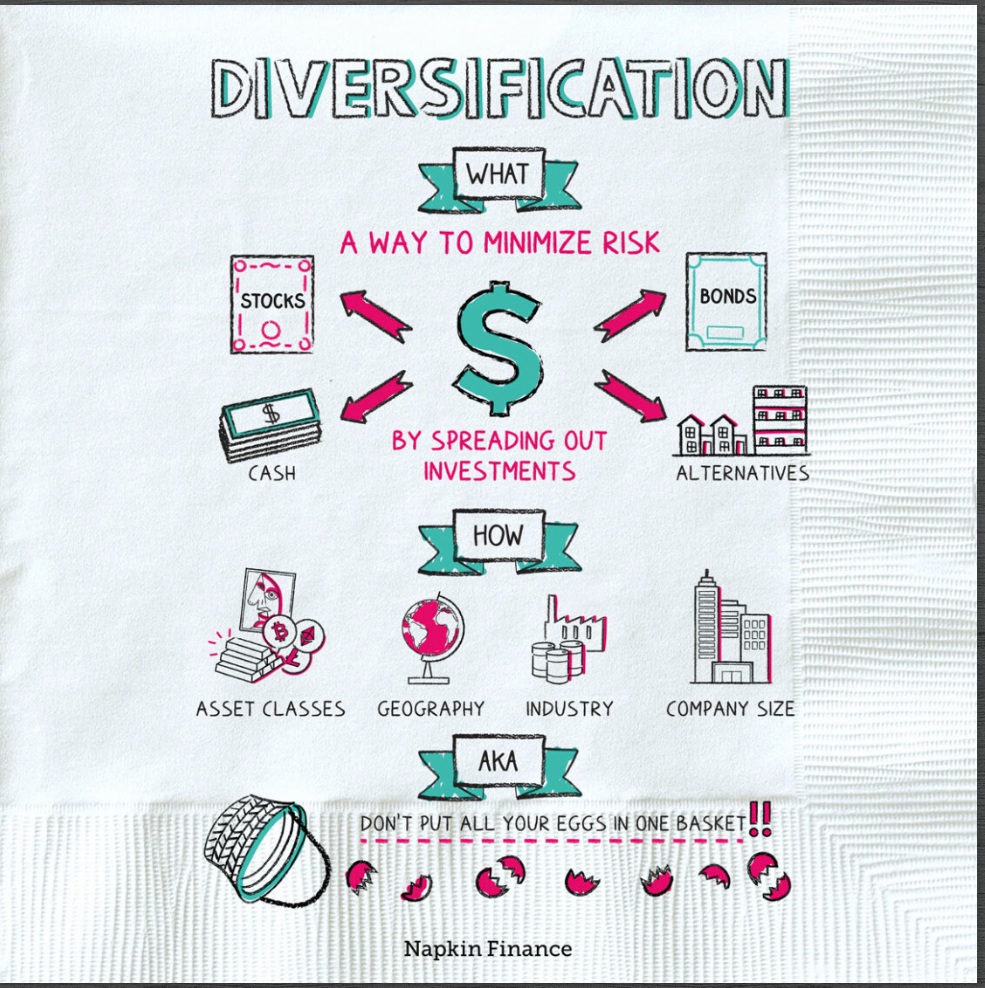
    I used to enjoy Jim Cramer’s “Am I Diversified?” segments because they raised a question every investor should ask: Do I truly have a diversified financial foundation? It is easy to believe you are diversified because you own several different stocks, but if those companies are all in similar industries—such as food, beverages, snack foods, or retail—they may be affected by many of the same economic pressures.

    True diversification is about spreading risk across different types of assets, industries, and sources of income. A mix might include traditional investments, real estate, a business or franchise, cash reserves, insurance-based strategies, and, for some people, carefully considered alternative assets such as precious metals or digital assets. The goal is not to eliminate risk—nothing can do that—but to avoid having your entire financial future depend on one market, one industry, or one source of income.

    Many people rely heavily on workplace retirement accounts or stock portfolios because those are the options most often presented to them. But it is worth stepping back and asking: What do I own? What risks are concentrated in one place? What important pieces might be missing?

    I am not fond of financial industries that push only their own product while dismissing every other option as “too risky.” Every asset class carries its own risks, benefits, costs, and place in a broader strategy. Since the beginning of time, people have valued land and gold because, bottom line, God is not making any more dirt.

    That is why I believe investment real estate deserves a place in many long-term wealth conversations. Many high-net-worth individuals use real estate as part of their wealth-building strategy, and real estate can offer potential tax advantages depending on the property, ownership structure, and an individual’s circumstances. The important questions are not whether real estate is right for everyone, but what percentage of your overall strategy it should represent, what type of property may fit your goals, and how it works alongside your other assets.

    I am a licensed real estate broker and life insurance broker, but I will be the first to say: do not put all your eggs in one basket. Let’s look at what you already have, identify areas that may be overly concentrated or missing, and help point you in the right direction—or redirect what you are already doing—so you can have more informed conversations with your qualified advisors.

    You do not have to begin with a large amount of money. Starting with one dollar is still a start—because tomorrow will be here before you know it.

    This article is for educational purposes only and is not individualized investment, tax, or legal advice. I am not a Certified Financial Planner (CFP) or a Certified Public Accountant (CPA). All investments involve risk, and diversification does not guarantee a profit or protect against loss. Please consult qualified financial, tax, and legal professionals before making decisions based on your individual circumstances.

  • Why Generational Wealth Matters

    Why Generational Wealth Matters

    Why Generational Wealth Matters

    Generational wealth is about creating financial stability, options, and a stronger starting point for the people we love. When a woman is divorced, widowed, or unexpectedly left by a spouse, she can be financially devastated—sometimes permanently—especially if she has spent years focused on caregiving rather than managing the household income or investments.

    That is why I have led several Wealth Wellness for Women seminars. While these conversations are designed to help protect women, the principles matter for everyone: as the Girl Scout in me says, “Be Prepared”—for today, for your future, and for the people you love.

    Key Components of Generational Wealth

    • Capital and financial assets
    • Real estate
    • Business ownership
    • Intellectual property
    • Estate planning and legacy protection

    Today’s Wealth Wellness Talking Points

    • Invest in yourself
    • Set clear financial goals
    • Plan for retirement
    • Create passive-income opportunities
    • Review and diversify your investments
    • Build a wealth strategy
    • Use real estate to build wealth
    • Understand insurance and living benefits
    • Establish a financial-benefits plan
    • Create tax-efficient strategies
    • Maximize retirement accounts

    Financial wellness is not about becoming rich overnight. It is about making informed decisions today that can protect your future and create more choices for you and future generations.

    I am developing an updated Generational Wealth presentation for organizations and groups in various markets. If you would like to bring this conversation to your team, network, church, or community organization, please reach out to me.

  • Recommended Books for Business Owners Managers – by Cathy Criado

    These books have informed my approach to business, investing, and real estate. If you are evaluating a commercial property, building an investment strategy, or growing a business such as a dental practice or café, I would be glad to discuss the ideas most relevant to your goals.

    1. The Greatest Salesman in the World — Og Mandino

    This classic reminds us that sales success begins with character, discipline, and how we treat people. Its message is simple but powerful: build daily habits rooted in persistence, service, and belief in yourself.

    2. Rich Dad’s Increase Your Financial IQ — Robert Kiyosaki

    Kiyosaki encourages readers to improve the way they earn, protect, budget, invest, and use money. Financial intelligence is not just about making more—it is about making wiser decisions with what you have.

    3. Rich Dad’s Cashflow Quadrant — Robert Kiyosaki

    This book explores the difference between earning income from a job and building income through business ownership and investments. It challenges readers to think beyond working for money and toward creating assets that can produce cash flow.

    4. The 10X Rule — Grant Cardone

    Grant Cardone’s message is that most people underestimate the effort required to reach a meaningful goal. The book encourages ambitious action, consistency, and a willingness to do more than feels comfortable.

    5. Think and Grow Rich — Napoleon Hill

    This enduring personal-development book focuses on the power of clear goals, focused thinking, and persistence. It reminds us that success often begins with a definite purpose and the decision to keep moving forward when challenges appear.

    6. Good to Great — Jim Collins

    Jim Collins examines why some companies make the leap from being merely good to becoming truly exceptional. The book highlights disciplined people, thoughtful leadership, and consistent execution as foundations for lasting success.

    7. Eat Mor Chikin — S. Truett Cathy

    The founder of Chick-fil-A shares lessons from building a business with faith, service, and strong values at its center. It is a reminder that a successful company can grow while still treating customers and employees with genuine care.

    8. More Than a Hobby — David Green

    David Green shares the story and principles behind Hobby Lobby’s growth, emphasizing purpose, generosity, and conviction. This book shows that business ownership can be about more than profit—it can also reflect the values you choose to live by.

    9. The Dip — Seth Godin

    Seth Godin explains that every meaningful pursuit includes a difficult stretch where progress feels slow and discouragement is easy. The key is learning when to push through the right challenge and when to let go of something that no longer serves your goals.

    10. The Self-Directed IRA Handbook — Matt Sorensen

    This book introduces the idea of using retirement funds to invest beyond traditional stocks and mutual funds, including certain real estate opportunities. It also reinforces the importance of understanding IRS rules and working with qualified professionals before making decisions.

    11. Money: Master the Game — Tony Robbins

    Tony Robbins breaks down wealth-building principles and encourages readers to take an active role in their financial future. The central takeaway is that a thoughtful plan, long-term perspective, and consistent action can create greater financial confidence.

    12. The Miracle Morning — Hal Elrod

    Hal Elrod presents a morning routine built around quiet reflection, affirmations, visualization, reading, writing, and movement. It is a practical reminder that how we begin our day can shape our focus, energy, and follow-through.

  • Are You Ready for Commercial Real Estate?

    Are You Ready for Commercial Real Estate?

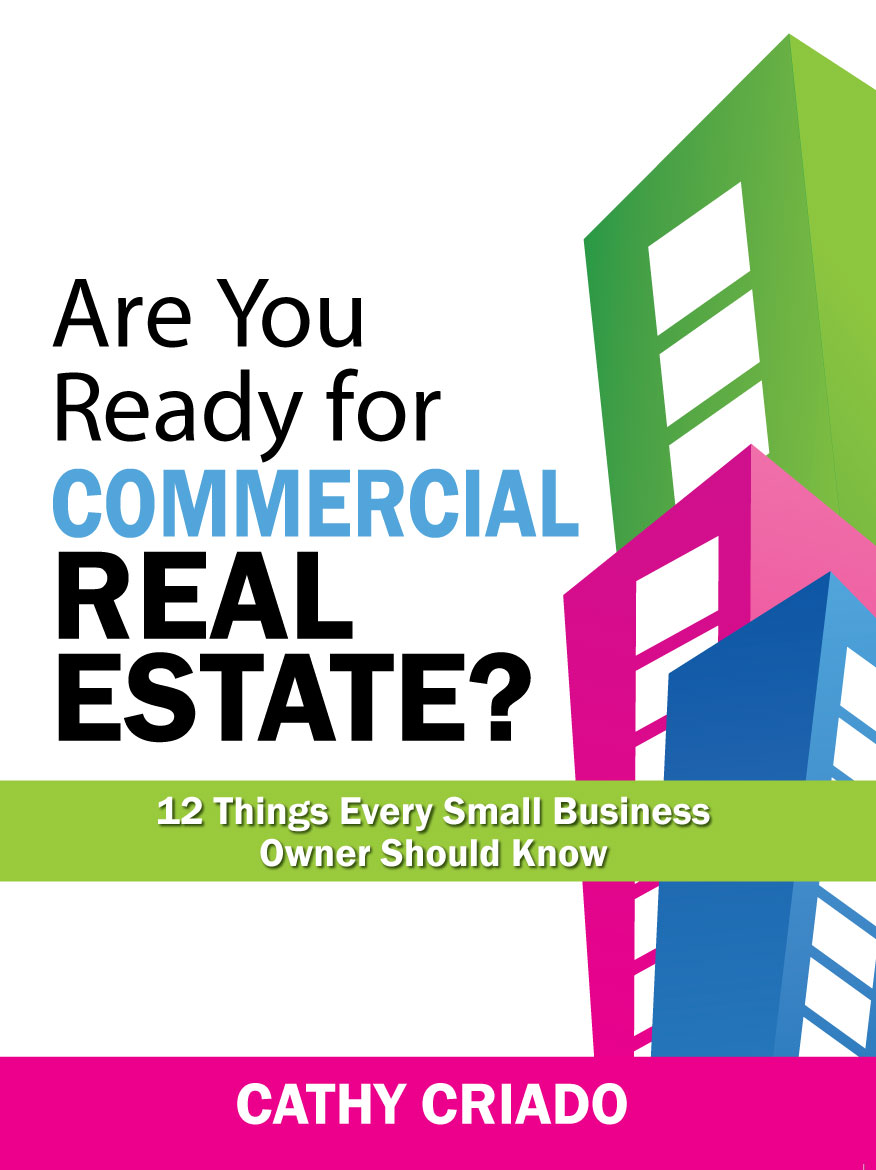
    Book cover for Are You Ready for Commercial Real Estate?

    For many small business owners, commercial real estate starts as a simple question: “Where can I afford to open my business?”

    That is the purpose of my book, Are You Ready for Commercial Real Estate? 12 Things Every Small Business Owner Should Know Before Leasing, Buying, or Investing.

    Commercial real estate is more than brick and mortar. Whether you lease an office, purchase a retail building, open a medical practice, or invest in income-producing property, the decisions you make can affect your business for years.

    Amazon

    I wrote this book because small business owners deserve practical guidance before making one of their largest financial commitments.

    Here are the core ideas behind the book.

    Think Like a Business Owner, Not Just a Tenant or Buyer

    Commercial real estate should be evaluated as a business tool. The right property supports your operations, your customers, your employees, and your long-term goals.

    Before looking at properties, get clear on your three-, five-, and ten-year goals.

    Due Diligence Is Not Optional

    A property may look perfect and still be a bad fit. Zoning, parking, signage, accessibility, utilities, and lease terms can all affect whether a location works for your business.

    Do not assume that because another business operated in a space, your business can operate there too.

    Choose Representation Carefully

    Your commercial real estate professional should be more than someone who unlocks doors. They should help you understand the market, evaluate options, and negotiate from a position of knowledge.

    A strong agent or broker helps you make decisions from a position of knowledge—not pressure.

    Understand the Financial Side

    A smart commercial real estate decision requires more than comparing asking prices. You need to understand the full cost of occupancy, including taxes, insurance, maintenance, build-out costs, financing, and operating expenses.

    When evaluating investment property, useful tools can include net operating income, capitalization rates, cash-on-cash return, and debt service coverage ratios.

    Lease, Buy, Build, or Invest With Purpose

    There is no one answer that works for every business owner. Leasing may preserve capital. Buying may build equity. Building may offer control. Investing may create income.

    The right answer depends on your business model, financial readiness, risk tolerance, and long-term goals.

    Start With the End in Mind

    Every business owner should have an exit strategy, even if retirement or a sale feels far away. A well-planned real estate decision can create flexibility and value when it is time to transition.

    These questions can shape the real estate decisions you make today.

    My goal is to help small business owners make real estate decisions that support growth, protect capital, and create opportunity.

    Are You Ready for Commercial Real Estate? 12 Things Every Small Business Owner Should Know Before Leasing, Buying, or Investing is available now.

    This article is for educational purposes and is not legal, tax, accounting, or investment advice.

  • Austin Multifamily Update: A Buyer’s View for 2026 and Q4 Outlook

    Buyer Perspective

    Austin’s multifamily market in 2026 may continue to offer buyers a more nuanced environment than the rapid-growth years that preceded it. New supply, evolving renter affordability, and changing capital markets can create both challenges and opportunities. For buyers, the central question may be whether an asset’s current income and long-term location justify the required basis and improvement plan.

    What Buyers May Watch

    • Supply and concessions: Monitor competing deliveries, effective rents, and lease-up performance in the immediate trade area.
    • Affordability: Rent growth may be shaped by household budgets as much as by headline population gains.
    • Location quality: Proximity to employment, transit, education, and daily conveniences may help differentiate assets.
    • Basis discipline: Conservative acquisition pricing and realistic renovation assumptions may be especially important.

    Q4 2026 Outlook

    By Q4 2026, Austin could move toward a more balanced multifamily landscape if demand absorbs a meaningful share of available inventory. That projection is uncertain and may vary significantly by submarket. Buyers may find the strongest opportunities where a property has durable location advantages, manageable capital needs, and a business plan that does not depend on aggressive rent growth.

    Austin acquisitions may benefit from patience, precise comparables, and a plan built for multiple market outcomes.

    Practical Next Steps

    Study effective rents, concessions, renewal behavior, construction activity, taxes, insurance, and deferred maintenance before finalizing an offer. Stress-test the investment for slower rent growth, longer stabilization, and higher operating costs.

    This article is general market commentary only and is not investment, legal, or tax advice. Market conditions and projections can change; consult qualified advisors before making decisions.

  • Houston Multifamily Update: A Buyer’s View for 2026 and Q4 Outlook

    Buyer Perspective

    Houston’s scale and economic diversity can create a broad range of multifamily acquisition scenarios in 2026. Buyers may find different conditions across employment nodes, suburban growth areas, and established urban neighborhoods. The market’s depth can support liquidity, but it also requires a detailed understanding of local supply, insurance exposure, operating costs, and renter preferences.

    What Buyers May Watch

    • Submarket divergence: Demand and concessions may differ materially between neighborhoods and product types.
    • Insurance and resilience: Property-specific insurance costs, deductibles, and flood-related considerations deserve early review.
    • Employment drivers: Medical, energy, logistics, port activity, and professional services may influence renter demand differently by area.
    • Operational upside: Older assets may offer improvement potential, but capital needs should be fully underwritten.

    Q4 2026 Outlook

    By Q4 2026, Houston may present a mix of stabilized opportunities and value-add situations, depending on the pace of supply absorption and financing availability. Buyers who maintain conservative assumptions around expenses, insurance, and rent growth may be better positioned to compare opportunities across the metro. No market-wide outcome is guaranteed, and local conditions may change quickly.

    Houston rewards buyers who underwrite the block, the building, and the business plan, not just the headline market.

    Practical Next Steps

    Compare in-place operations with verified market data, inspect physical condition carefully, and model a range of insurance, tax, occupancy, and financing outcomes. A clear plan for capital improvements and property management is essential before closing.

    This article is general market commentary only and is not investment, legal, or tax advice. Market conditions and projections can change; consult qualified advisors before making decisions.

  • New Braunfels Multifamily Update: A Buyer’s View for 2026 and Q4 Outlook

    Buyer Perspective

    New Braunfels remains a market buyers may evaluate through the lens of growth, connectivity, and asset-specific execution. Its position between San Antonio and Austin, combined with continued household formation and regional employment access, may support multifamily demand over time. At the same time, a smaller market can experience sharper shifts in supply, leasing, and pricing than larger metros.

    What Buyers May Watch

    • New construction: Track deliveries and concessions closely, especially near major growth corridors.
    • Resident demand: Consider the mix of local employment, commuters, families, and lifestyle-driven renters.
    • Property positioning: Unit finishes, amenities, and maintenance standards may influence leasing velocity.
    • Exit assumptions: Use measured rent-growth and cap-rate assumptions rather than relying on recent historical gains.

    Q4 2026 Outlook

    By Q4 2026, New Braunfels may offer selective acquisition opportunities if supply is absorbed unevenly or sellers face tighter financing conditions. Properties with convenient access to employment, retail, and regional transportation could continue to attract attention. Buyers should expect performance to vary by location, vintage, and operating quality rather than move uniformly across the market.

    In a fast-growing corridor, careful due diligence can be more valuable than broad market enthusiasm.

    Practical Next Steps

    Review competing properties, current concessions, renewal trends, utility structures, insurance, taxes, and anticipated capital expenditures. Buyers may also benefit from testing whether a property can perform if lease-up takes longer than expected.

    This article is general market commentary only and is not investment, legal, or tax advice. Market conditions and projections can change; consult qualified advisors before making decisions.

  • San Antonio Multifamily Update: A Buyer’s View for 2026 and Q4 Outlook

    Buyer Perspective

    San Antonio enters 2026 with a multifamily market that may reward disciplined buyers who focus on property-level operations, submarket fundamentals, and realistic capital assumptions. Population growth, employment diversity, and relative affordability continue to support long-term housing demand, while the pace of new supply and the cost of capital may keep near-term performance uneven across the metro.

    What Buyers May Watch

    • Supply absorption: New deliveries may create leasing pressure in select corridors, particularly where construction has been concentrated.
    • Operating performance: Buyers may find value in assets with a clear path to improved occupancy, expense controls, or resident experience.
    • Financing discipline: Debt structure, interest-rate sensitivity, and reserve planning remain central to underwriting.
    • Submarket selection: Access to employment centers, medical districts, education, and transportation may matter more than metro-wide averages.

    Q4 2026 Outlook

    By Q4 2026, San Antonio could see a more balanced buyer environment if deliveries moderate and demand continues to absorb available units. That outcome is not assured. Well-located properties with durable cash flow may remain competitive, while assets facing deferred maintenance, weak leasing momentum, or aggressive prior underwriting could present more negotiable opportunities.

    For buyers, the opportunity may be less about timing the entire market and more about matching a specific asset to a conservative business plan.

    Practical Next Steps

    Evaluate rent rolls, concessions, tax exposure, insurance costs, capital needs, and comparable supply at the submarket level. A thoughtful acquisition plan should also test downside scenarios for occupancy, rent growth, expenses, and refinancing.

    This article is general market commentary only and is not investment, legal, or tax advice. Market conditions and projections can change; consult qualified advisors before making decisions.